QBTS stock fell approximately 11% during Tuesday’s regular trading session after D-Wave Quantum reported third-quarter revenue above Wall Street expectations but disclosed weaker quarterly bookings, widening operating losses and declining cash reserves. The results, released before the November 10 market open, shifted investor attention toward the company’s ability to turn its substantial customer commitments into recognized revenue.
D-Wave Quantum (NASDAQ: QBTS) reported revenue of $4.51 million, compared with analyst estimates ranging from $4.33 million to $4.37 million. Revenue increased 21% year over year and approximately 46.5% from the previous quarter’s $3.08 million. However, the company recorded a loss of $0.13 per share, wider than the approximately $0.10 loss analysts expected.
Shares traded at $10.21 at 1:10 p.m. ET, down 10.99% from Monday’s $11.47 closing price, according to StockAnalysis. The stock had opened at $11.06 and traded as low as $10.11. Monday’s close represented a 7.40% gain, following an 18.01% advance on Friday, making Tuesday’s decline a reversal of a two-session rebound.
The results present a mixed picture. D-Wave has accumulated significantly more future business than a year ago, but the latest quarter generated only $1.9 million in new bookings, while operating expenses continued rising much faster than revenue. Management expects a substantial increase in fourth-quarter revenue from planned quantum computer deliveries, placing considerable weight on execution before year-end.
D-Wave Beats Revenue Estimates but Misses Earnings Expectations
D-Wave’s official third-quarter earnings release confirmed revenue of $4.513 million for the three months ended September 30, 2026. That exceeded the $4.37 million consensus reported by MarketBeat by approximately $143,000, or 3.3%.
The outcome also exceeded the more conservative revenue outlook management provided in August. During the second-quarter earnings call, then-Chief Financial Officer John Markovich said third-quarter revenue would likely increase modestly from approximately $3.1 million because two anticipated system deliveries were expected in the fourth quarter.
Although the resulting sequential growth was approximately 46.5%, the absolute increase amounted to only around $1.43 million. The discrepancy between the company’s cautious guidance and the higher analyst consensus had been a central question ahead of the announcement.
FinanceFeeds examined that issue in its November 4 QBTS stock analysis, which highlighted the importance of delayed system deliveries and the concentration of expected annual revenue in the final quarter.
D-Wave’s revenue growth came primarily from professional services and quantum computing as a service, known as QCaaS. Professional services revenue increased by approximately $1.5 million year over year, while QCaaS revenue grew by $800,000. System sales revenue declined by $1.5 million.
The changing revenue mix affected profitability. GAAP gross profit declined 11% to $2.4 million, while gross margin fell to 52.9%, down from 71.4% a year earlier. Management attributed the reduction primarily to the higher proportion of professional services, which carry lower margins, alongside additional stock-based compensation.
GAAP operating expenses increased 84% to $55.9 million, approximately 12 times quarterly revenue. The company reported a $48.2 million net loss, compared with $140 million a year earlier. Much of that improvement reflected the absence of substantial noncash warrant-related charges recorded in the previous year, rather than stronger operating profitability.
Adjusted EBITDA loss widened 83% to $37.7 million, reflecting continued spending on technology development and commercial expansion.
Quarterly Bookings Fall While Nine-Month Orders Surge
Bookings provide another view of D-Wave’s commercial progress. The company reported third-quarter bookings of $1.9 million, down 19% from approximately $2.3 million in the comparable 2025 quarter.
For the first nine months of 2026, however, bookings reached $37.4 million, representing an increase of 611% year over year. The substantial difference reflects the timing of large transactions, including a $20 million quantum computer agreement with Florida Atlantic University.
On Tuesday’s earnings call, Acting CFO Greg Golkov said the dollar value of D-Wave’s sales pipeline had expanded more than 75% from the end of June and more than tripled since the end of 2025. Management attributed the increase to growing interest in system purchases.
The distinction between bookings and revenue remains critical. Bookings measure customer orders expected to generate future revenue, whereas revenue is recognized as contractual performance obligations are satisfied. Large system orders can therefore support the company’s longer-term outlook without immediately increasing quarterly sales.
D-Wave reported remaining performance obligations of $38.3 million at September 30, up 1,221% from $2.9 million a year earlier. However, the balance declined from $40.7 million at the end of June.
Management expects approximately 59% of the September balance to become recognized revenue within 12 months and 71% within 24 months. Investors will need to assess whether those commitments convert at the expected pace.
The company’s balance sheet also weakened during the quarter. Cash and marketable investment securities declined to $503.4 million from $546.2 million at June 30, a decrease of approximately $42.8 million.
D-Wave disclosed a definitive agreement with the US Department of Commerce providing access to up to $100 million under the CHIPS and Science Act. The financing is conditional on meeting specified milestones, and management said no funds had been received under the arrangement as of September 30.
QBTS Stock Slides as Investors Assess the Earnings Mix
Tuesday’s trading showed that the modest revenue beat was insufficient to sustain the rally that carried QBTS higher during the previous two sessions.
The shares initially traded near $10.93 before the opening bell, down approximately 4.7%, according to the earlier FinanceFeeds premarket report on D-Wave’s earnings and bookings decline. Selling intensified during regular trading, with the stock falling approximately 11% by early afternoon.
The reaction came despite management highlighting customer deployments and technological progress. D-Wave reported that NTT DOCOMO implemented another production application using its hybrid quantum technology. The company also delivered an Advantage2 quantum computer for installation in Como, Italy, and introduced a beta version of its gate-model simulator.
Nevertheless, investors are weighing those developments against operating losses, the timing of commercial system sales and the gap between future orders and current revenue.
The stock’s decline also followed a substantial recovery from its November 5 intraday low of $8.48. After closing at $9.05 that day, QBTS advanced to $10.68 on Friday and $11.47 on Monday before reversing following the results.
The volatility illustrates the extent to which expectations for future commercialization can influence a company generating relatively limited quarterly revenue.
IonQ’s Q3 Results Set a Different Benchmark for Quantum Stocks
D-Wave’s report follows a considerably stronger revenue announcement from rival IonQ, which reported third-quarter results on November 5.
According to IonQ’s official financial results, revenue reached $173.83 million, exceeding the approximately $141.63 million analyst expectation cited ahead of the release. The company increased its full-year revenue guidance to $505 million to $515 million.
However, the revenue comparison requires qualification. IonQ’s reported total included $83.5 million from SkyWater Foundry Services, while its IonQ Platform segment contributed $90.3 million. Acquisitions therefore account for part of the difference in reported revenue scale.
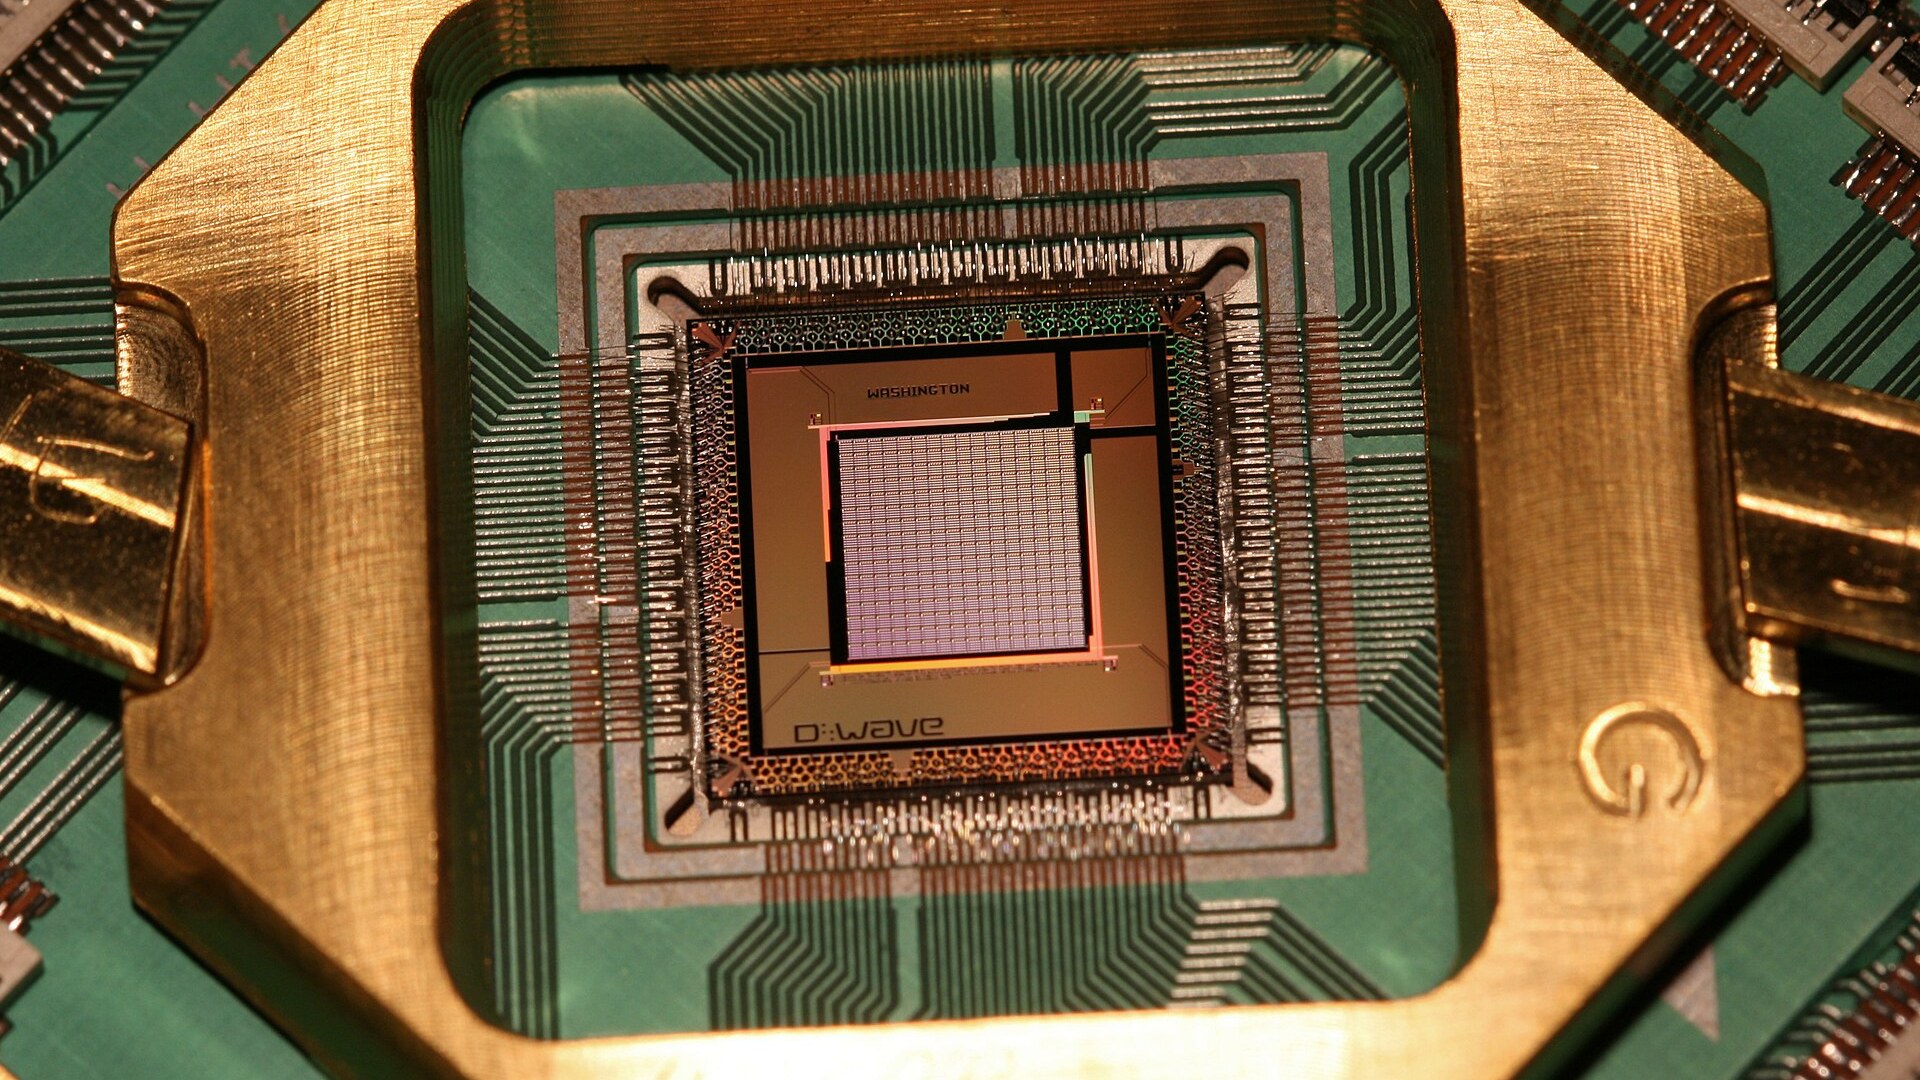
The two companies also use different quantum computing architectures and commercial approaches. D-Wave offers quantum annealing systems and is developing gate-model technology, while IonQ’s platform includes trapped-ion computing and other quantum technologies.
Still, IonQ’s performance demonstrates why investors are increasingly examining recognized revenue, customer deployment schedules and operating costs rather than relying exclusively on future bookings or technological announcements.
Fourth-Quarter System Deliveries Become D-Wave’s Next Test
The immediate focus now turns to D-Wave’s expected fourth-quarter system sales, particularly the $20 million agreement with Florida Atlantic University.
During Tuesday’s earnings conference call, Golkov said D-Wave still expects to deliver that system and recognize a substantial portion of the associated revenue during the fourth quarter. Additional revenue related to installation and calibration is expected to be recognized in early 2027.
That schedule leaves an important execution risk. Because system transactions are much larger than recurring QCaaS contracts, their delivery dates can produce substantial fluctuations in quarterly revenue.
Investors should monitor whether D-Wave completes its anticipated system shipments before December 31, whether the associated revenue is recognized on schedule and how much installation-related income is deferred into 2027.
Gross margins will also warrant attention. A higher contribution from system sales could materially change the revenue mix compared with the service-heavy third quarter, although the effect on profitability will depend on the economics of the individual contracts.
Management’s longer-term plans include developing a 100,000-qubit annealing computer and a 10,000-qubit gate-model system. These initiatives may expand the company’s addressable market, but they also require continued investment while its existing commercial business remains loss-making.
The third-quarter results therefore leave investors with a clearer near-term test than the modest revenue beat alone. D-Wave has substantial contracted business, a growing sales pipeline and more than $500 million in cash and marketable securities. Yet quarterly bookings fell, operating costs increased and recognized revenue remains small relative to its spending.
For QBTS stock, the next major question is whether the expected fourth-quarter deliveries can convert that backlog into a meaningful increase in revenue. The timing and profitability of those shipments will provide stronger evidence of commercial progress than Tuesday’s headline earnings beat.