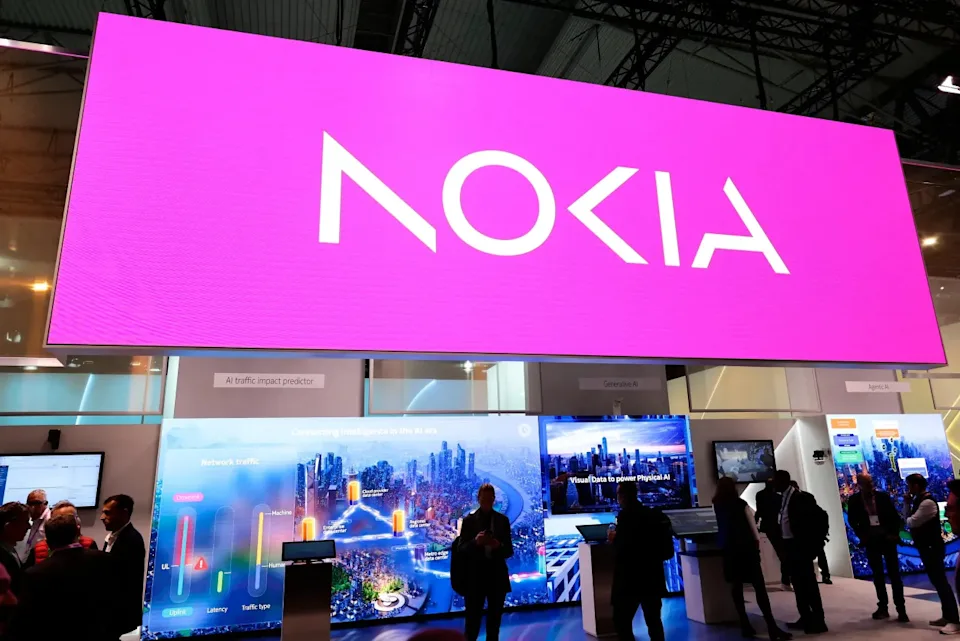
Nokia stock (HEL: NOKIA) closed 9.72% lower at €7.43 in Helsinki on Thursday, October 22, after the Finnish network equipment maker cut its 2026 free-cash-flow conversion forecast and reported €357 million in restructuring and integration charges. The selloff followed third-quarter results showing comparable operating profit of €605 million, approximately 34% above analyst expectations.
Nokia’s NYSE-listed shares (NYSE: NOK) extended the decline, trading at $7.89, down 14.76%, at 21:55 Finnish time, according to the company’s investor-relations page. The US session was still underway.
Net sales rose 10% to €5.15 billion, while AI and cloud customer orders increased 118%. The market reaction nevertheless focused on cash generation and the gap between Nokia’s adjusted earnings and reported profitability.
The company lowered its expected free-cash-flow conversion to 35%–55% of comparable operating profit, from 55%–75% previously, and increased its annual restructuring charge assumption to €1.1 billion.
Nokia’s €605 Million Profit Beats Forecasts, but Reported Earnings Fall
Nokia reported third-quarter net sales of €5,154 million, an increase of 10% year over year on a reported basis and 9% at constant currency and portfolio. The figure exceeded the approximately €5.05 billion consensus estimate collected by the company.
Comparable operating profit increased 35% from €448 million to €605 million, substantially exceeding the €453 million analyst consensus cited by Reuters.
The comparable operating margin improved by 220 basis points to 11.7%, reflecting higher revenue and operating efficiencies. Comparable diluted earnings per share from continuing operations rose to €0.09 from €0.06.
However, reported operating profit fell 22% to €196 million, compared with €252 million a year earlier. The reported operating margin contracted to 3.8% from 5.4%, while reported diluted EPS from continuing operations was €0.03.
The €409 million difference between comparable and reported operating profit highlights the significance of adjustments excluded from Nokia’s preferred profitability measure. Restructuring and integration charges accounted for approximately €357 million during the quarter, according to financial reporting on the results.
Those charges help explain why comparable profitability improved while reported operating profit deteriorated. They do not account for the entire difference between the two measures.
Nokia’s net cash and interest-bearing financial investments also fell 14% year over year to €2,584 million, from €3,001 million.
Why Nokia Cut Its Free-Cash-Flow Conversion Forecast
The most consequential guidance change concerned cash generation rather than operating earnings.
Nokia reduced its expected 2026 free-cash-flow conversion to 35%–55% of comparable operating profit, compared with the 55%–75% range provided in its July 23 second-quarter report.
Both ends of the guidance range fell by 20 percentage points.
The company attributed the revision to higher working-capital requirements intended to secure component supply and support growth opportunities in 2027, alongside accelerated restructuring activity.
Nokia now expects to invest an additional €400 million in working capital during 2026. Its third-quarter free cash flow was approximately negative €99 million.
The company also raised anticipated annual restructuring charges from €800 million to €1.1 billion and associated cash outflows from €700 million–€800 million to €800 million–€900 million.
These revisions carry financial consequences even though Nokia maintained its full-year comparable operating profit guidance of €2.1 billion–€2.6 billion.
At the €2.35 billion midpoint of that profit range, the old 55%–75% conversion assumption implied €1.29 billion–€1.76 billion of free cash flow. The revised 35%–55% assumption implies approximately €823 million–€1.29 billion.
That is a €470 million reduction at either end of the illustrative range, holding operating profit constant. It explains the financial importance of the conversion revision without requiring a downgrade to Nokia’s earnings target.
Capital expenditure assumptions were lowered to €750 million–€850 million from €800 million–€900 million, partly because some manufacturing-related payments will move into 2027.
The lower capital expenditure estimate provides some relief, but does not eliminate the additional working-capital and restructuring requirements.
The relationship between profitability and cash generation was already a central concern in FinanceFeeds’ September Nokia stock analysis, which highlighted the company’s negative second-quarter cash flow and reliance on stronger second-half earnings.
AI Orders Jump 118% as Network Infrastructure Revenue Rises 17%
Nokia’s latest results provided substantial evidence of accelerating demand for its AI and data-center networking equipment.
Net sales to AI and cloud customers increased 123% year over year, while order intake rose 118%. The company secured approximately €1.5 billion in new AI and cloud orders during the quarter.
Network Infrastructure generated €2,158 million in revenue, up 17% on a reported basis and 15% at constant currency and portfolio. IP Networks sales increased 43%, while Optical Networks grew 18%.
Mobile Infrastructure revenue rose 5% to €2,902 million, supported partly by revenue originally expected in the fourth quarter being recognized earlier.
That acceleration matters when assessing Nokia’s outlook. Some third-quarter mobile revenue represents a change in timing rather than an additional contribution to full-year demand.
Chief Executive Justin Hotard said the company expects combined Optical and IP Networks revenue to grow between 25% and 30% in 2027.
Nokia also expects to complete its Infinera integration by the end of 2026, one year ahead of its original schedule, with €200 million in net synergies.
The company is expanding its role in AI infrastructure through optical connectivity, IP routing and its AI-RAN partnership with Nvidia.
As FinanceFeeds previously examined in its analysis of Nvidia’s investment portfolio, Nokia is among the semiconductor company’s strategic equity investments, connecting the telecom equipment maker to broader AI infrastructure spending.
However, a growing order book does not immediately translate into free cash flow. Securing components and carrying inventory ahead of future deliveries can increase near-term funding requirements.
Nokia’s Fourth Quarter Must Deliver a Sharp Earnings Increase
Nokia maintained its 2026 comparable operating profit guidance of €2.1 billion–€2.6 billion and expects full-year profit to finish above the midpoint of that range.
With €1.34 billion of comparable operating profit recorded during the first nine months, Nokia needs more than €1.01 billion in the fourth quarter to achieve that ambition.
That would be substantially higher than the €605 million earned in the third quarter.
Management expects fourth-quarter net sales to increase between 20% and 24% sequentially. Applied to Q3 revenue of €5.15 billion, this implies approximately €6.19 billion–€6.39 billion in fourth-quarter sales.
The company also expects a strong sequential increase in operating profit.
The immediate investment question is whether higher sales and operating leverage can deliver those earnings while Nokia simultaneously increases working capital and accelerates restructuring spending.
Its cash-conversion downgrade has also changed the context for earlier valuation expectations. FinanceFeeds’ analysis of the optical networking supply chain highlighted Nokia’s exposure to expanding data-center infrastructure demand, an opportunity that now comes with greater near-term cash requirements.
The next decisive financial update is scheduled for January 28, 2027, when Nokia plans to publish its fourth-quarter and full-year results.
Investors will be able to assess whether the expected fourth-quarter earnings recovery materialized, whether working-capital investment stabilized and how much free cash flow the company generated against its reduced conversion forecast.
The October 22 results established that Nokia’s AI networking business is expanding rapidly. The sharper test for Nokia stock is whether that growth can produce cash returns after the costs of securing supply and restructuring the business are accounted for.